The best travel insurance for Bali starts with your trip and eligibility, not a brand ranking. A two-week holiday, an extended stay and a move abroad involve different needs. Compare the appropriate product type before looking for a low premium.
I would first write down residence, destinations, travel dates, planned activities and the expenses you want protected. Then separate unexpected medical care, prepaid travel costs and ongoing healthcare. A plan addressing one need does not automatically address the others.
This guide compares researched directions from SafetyWing and Seven Corners. World Nomads also appears as an availability check during its ownership transition. No provider is presented as a universal winner for every Bali traveler.
Research date: October 13, 2026. The comparison uses official product pages, help material and current brochure text. SafetyWing’s public Essential description was accessible and selected benefits were reviewed. Its legal notice says the master policy governs discrepancies. No effective-version date was visible, and complete applicable contracts were not accessible for every product. I have not obtained a personal quote, bought a policy, submitted a claim or tested assistance. Obtain the current wording and a licensed insurer or adviser’s confirmation for your circumstances before purchasing.
Ownership disclosure: I own Ecommerce Paradise and Supplier Paradise. Their business resources do not supply insurance advice. Qualifying purchases through the SafetyWing referral earn me a commission at no additional cost to you. The documented referral reached SafetyWing with attribution parameters preserved. Other providers remain unlinked because their affiliate destinations are unverified.
Best travel insurance for Bali: product directions to compare
| Product direction | Research purpose | Eligibility question | Before purchase |
|---|---|---|---|
| SafetyWing Essential | Travel medical needs | Home country, age, itinerary and plan version | Current description of coverage and selected extras |
| SafetyWing Complete | Broader ongoing health needs | Applicable health and travel arrangements | Exact documents, eligibility and care requirements |
| Seven Corners Travel Medical Excluding USA | Eligible U.S.-resident travel outside the USA | Residence and state restrictions | Current Basic or Choice contract |
| Seven Corners Travel Medical Global | Eligible non-U.S.-resident travel outside primary residence | Residence and destinations | Current product contract and activity terms |
| World Nomads | Recheck new-policy availability | Current region and transition status | New-sale availability and applicable wording |
These directions are research candidates, not approved policies for your application. Residency filters deserve attention before benefit limits. Do not read a familiar company name as permission to choose any product from its catalog.
SafetyWing Essential and Complete address different needs
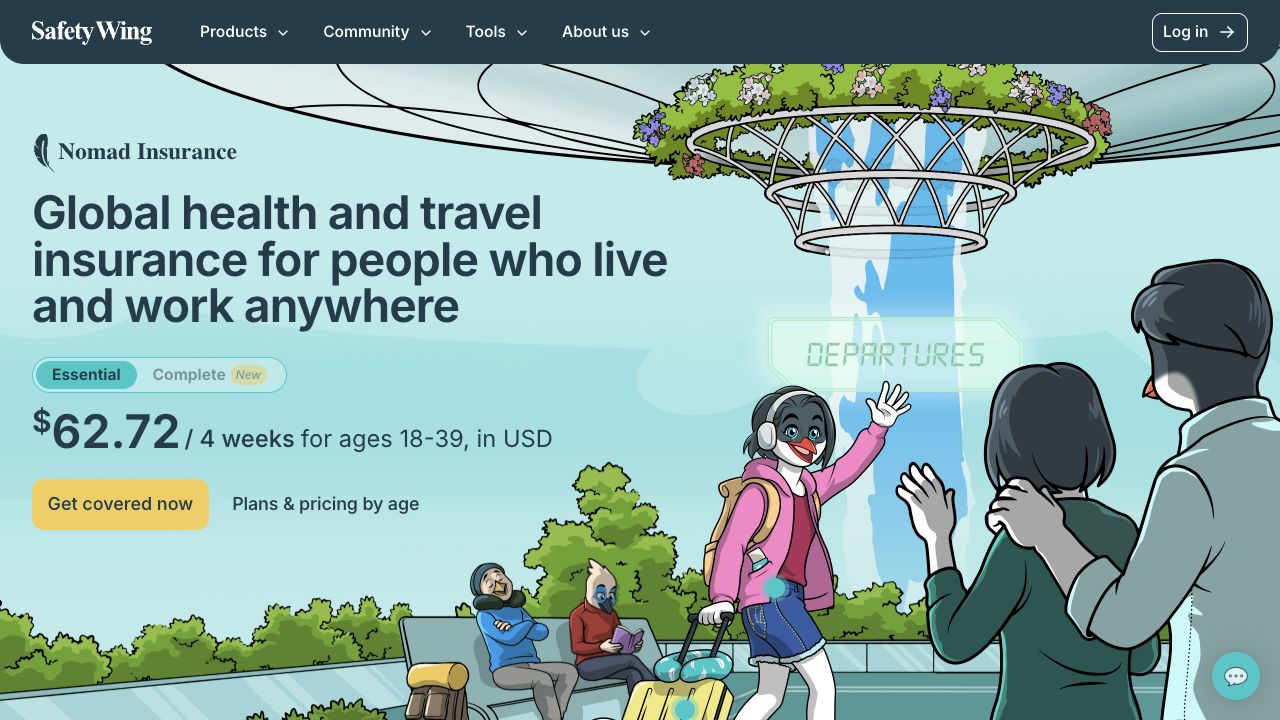
SafetyWing presents Essential as travel medical insurance and Complete as a broader health offering with travel protections. The inspected public age-18–39 examples showed Essential at US$62.72 per four weeks and Complete at US$177.50 per month. Different billing units and coverage designs prevent a simple price-only comparison.
Those public examples are not personal quotes. Identify the selected product, region, start date and extras. A familiar headline premium does not establish eligibility or reimbursement for a future expense.
My Essential versus Complete guide addresses the provider-specific comparison. Use the documents applicable to your application rather than assuming every older article describes your current version.
Seven Corners separates resident groups
The currently linked Travel Medical Excluding USA brochure describes a U.S.-resident direction excluding New York. Travel Medical Global describes a non-U.S.-resident direction for travel outside the primary-residence country and excluding the USA. Both brochures describe interim travel medical coverage, not a replacement for comprehensive health insurance.
The brochures identify different underwriters and defer to the full plan. This review did not access all currently linked certificates. Do not transfer one product’s benefits, activity rules or residency assumptions into another product with a similar name.
Recheck World Nomads before treating the offer as available
World Nomads’ member page displayed a temporary systems-change notice associated with the IMG ownership transition. Its timeline still described an anticipated transaction window rather than a confirmed closing date. Existing-policy continuity statements do not verify current new-policy availability or unchanged new-sale terms.
Request the product and documents offered for your actual residence. Do not rely on an older Bali landing page, a different country’s customer notice or a saved marketing screenshot as proof of an available policy.
Write a trip profile before requesting quotes
Use a private note for the facts relevant to the comparison. Record departure, arrival, return and transit dates. Include other destinations and home visits rather than describing the whole itinerary with the word Bali.
Distinguish citizenship, residence and the policy’s defined home country. These terms are not interchangeable. A mailing address alone does not establish the insurer’s residence definition, and a long stay deserves more careful review than a short holiday assumption.
Identify planned work and activities accurately. Remote desk work, a guided activity and a rental-scooter journey raise different questions. Ask the insurer about the activity you intend to perform instead of selecting a broad adventure label and assuming every activity is included.
Keep medical and identity information in the insurer’s appropriate private process. This guide does not need your passport number, symptoms or policy account access. A publicly shared comparison worksheet should exclude those details.
Separate medical cover from prepaid-trip protection
Travel medical insurance focuses on eligible health expenses while traveling. Trip-protection products address specified travel losses under their own conditions. Ongoing health coverage addresses another set of needs. Product labels help organize research, but the actual contract governs the benefits.
Make an inventory of nonrefundable reservations and existing refund rights. Record what the airline, accommodation provider and other businesses owe under their terms. Insurance should not be credited with protection you already receive elsewhere, or assumed to cover every remaining loss.
SafetyWing’s updated Essential cancellation help distinguishes reimbursement of existing bookings from narrower transportation-delay and alternative-accommodation benefits. A delay allowance does not establish reimbursement of the original flight or hotel. Read covered reasons, timing, documentation and limits together.
Changing your mind is also different from an insured event. Do not assume cancellation-for-any-reason protection exists because a plan mentions interruption or delays. Ask for the relevant benefit wording before building a budget around repayment.
Review scooters and activities before the trip
A scooter rental shop accepting payment does not establish lawful licensing or insurance eligibility. Verify the relevant vehicle class, license requirements, safety equipment and insurance conditions before riding. A regular car license should not be treated as proof of permission for every motorcycle.
SafetyWing’s June 2026 help says riders and passengers on vehicles larger than 50cc need the Adventure Sports add-on for the described Essential accident or injury eligibility. Appropriate licensing and safety equipment still matter. The help also distinguishes exclusions involving intoxication, racing, property liability and third-party medical expenses.
The provider-specific statement needs review against the applicable description of coverage. Do not copy the add-on threshold into another insurer’s policy. Seven Corners’ public Excluding USA page describes separate adventure-coverage conditions for motorcycle, scooter and micromobility use.
List surfing, diving, hiking and any guided excursion separately. Describe the actual activity, not the tour operator’s marketing category. Confirm the level, equipment, operator and conditions relevant to the policy instead of assuming a single optional package settles every question.
Handle medical history and timing carefully
Definitions of pre-existing conditions differ by contract and version. Prior symptoms, recommended care and medication history deserve accurate private disclosure where required. Do not substitute a blog’s brief description for the insurer’s questions or a qualified assessment.
Updated Essential help describes a limited emergency-treatment exception alongside the general pre-existing exclusion. Its conditions do not establish routine coverage for chronic, congenital or progressively worsening conditions. Ask the insurer how your circumstances fit the actual wording without expecting this article to determine eligibility.
Timing requires the same care. Updated Essential help distinguishes benefit-specific waiting periods from additional documentation for certain incidents within the first 72 hours after purchase. A blanket statement about immediate coverage or a universal 72-hour waiting period would miss those distinctions.
Obtain confirmation of the start date and time, relevant waiting periods and any underwriting conditions before assuming protection is active. Buying after symptoms begin does not establish coverage of the existing problem. This guide gives no diagnosis or instruction to delay medical care.
Compare limits, deductions and payment arrangements
A large medical maximum is one part of the comparison. Ask whether particular benefits have separate caps, age-dependent limits or deductions. Read the relevant limit with the eligibility conditions rather than treating the largest number on a page as the amount available for every expense.
Separate the deductible, any cost-sharing and exclusions. These describe different reasons an expense might remain yours. A zero-deductible label does not imply every service is covered or every hospital charge accepted.
Review whether coverage is primary or secondary and how existing insurance affects a claim. Do not assume two policies double the available payment. Ask each provider about the actual coordination process and retain the relevant responses.
Direct billing, assistance and guaranteed payment also differ. A provider directory does not establish approval of a particular bill. Confirm the insurer’s process for authorization and payment without treating a testimonial or contact-center response as a binding claims decision.
Keep evacuation, rescue and liability separate
Medical evacuation concerns an eligible transport arrangement under specified conditions. Search and rescue addresses another situation. Repatriation, political evacuation and a return trip involve separate benefits and definitions. Similar travel words do not establish equivalent protection.
SafetyWing’s updated exclusions help lists search-and-rescue services separately. Do not use a medical-evacuation headline to imply payment for every helicopter operation. Ask the insurer which organization arranges an eligible service and what approval requirements apply.
Liability is another distinct issue. Damage to a rented vehicle, injury to someone else and your own eligible medical expenses require separate review. A statement about your medical accident benefit does not establish protection against every third-party cost.
For a planned excursion, keep the operator’s responsibilities and cancellation terms alongside the insurance review. An operator’s permission to participate does not replace your policy. Avoid undertaking an activity based solely on a blog recommendation.
Review possessions and travel interruptions realistically
Checked-baggage benefits, theft benefits and protection for business equipment are different. Read the covered item categories, custody requirements, evidence and exclusions. A laptop used for client work should not be assumed protected because the policy mentions luggage.
Record an item’s value and the policy’s relevant per-item and total limits. Review existing cover before purchasing an extra product. Keep proof of ownership privately, without uploading sensitive receipts into a public travel discussion.
Trip interruption, delays and inaccessible accommodation also have defined triggers. Preserve booking confirmations and relevant communications. A stressful experience does not establish a covered reason by itself, and a promotional description does not guarantee a payment schedule.
Do not count anticipated reimbursement as cash already available for the trip. Maintain practical access to funds for unexpected expenses. This is travel planning, not a determination of your insurance claim or financial capacity.
Best travel insurance for Bali: use a consistent comparison record
Compare candidates against the same trip profile. Record the product name, applicant region, quotation date, applicable policy version, start and end times, selected extras and total premium. An outdated quote should not silently replace a current offer.
In a fictional comparison, one traveler needs a short overseas holiday policy and another needs ongoing care during a longer stay. Their product choices deserve different research. This example describes decision inputs, not customers I advised or outcomes I measured.
Write each unresolved requirement as a specific question. For example, ask how the selected policy handles your planned activity, a home visit or a nonrefundable booking. A broad request for the best plan invites a broad answer instead of evidence about your actual need.
Keep the insurer’s response beside the matching contract section. Record who supplied the explanation and when. If the explanation conflicts with the document, request clarification rather than editing the worksheet until the inconsistency disappears.
Leave an unanswered item marked unresolved. Missing evidence is not a positive result. Do not choose a candidate solely because its lower premium makes the spreadsheet look complete.
Prepare an accessible assistance record
After an appropriate policy is issued, retain its certificate, current wording and official assistance instructions. Keep access available when connectivity is poor. Share necessary details with a trusted travel companion or contact through a private channel.
Check the process for contacting assistance and identifying your policy. Distinguish an urgent medical situation from an administrative claim question. Seek appropriate urgent help when needed rather than waiting for a blog comment or insurance comparison to resolve the problem.
Keep receipts, relevant reports and communications organized for any later authorized claim. Follow the insurer’s documentation process and deadlines. Do not invent incident details or alter documents to fit a benefit.
For an unresolved claim, use the provider’s formal clarification and appeal routes. Ask which document or eligibility issue requires attention. An appeal is not a guarantee of reversal, and this guide supplies no claim outcome prediction.
Review official travel guidance without treating advice as coverage
The UK government’s Indonesia advice was marked current October 13, 2026. Its update removed a general advice-against-all-travel position for volcanoes while retaining attention to local exclusion zones and directions. Do not repeat an outdated blanket volcanic travel ban.
Review advice relevant to your nationality and itinerary, including transit countries. An official warning, an airline disruption and a policy exclusion involve different sources. Ask how the applicable contract treats the situation rather than treating a government page as an insurance certificate.
Check entry and visa requirements separately through the relevant authorities. A provider’s visa-letter feature does not prove acceptance for every visa or residence arrangement. Do not substitute this article for a current immigration requirement or individual application decision.
Keep remote-business planning separate from insurance advice
For readers operating an online store while traveling, assign customer support and supplier communication before departure. My high-ticket dropshipping guide explains the retail model I teach. An insurance policy does not keep orders moving or answer customer questions.
The niches list supports category research for an online business. Choose a model fitting your skills and available time rather than assuming travel creates an income source.
My supplier research guide addresses commercial verification. Confirm delivery and support responsibilities before leaving the team with unresolved supplier promises.
Supplier Paradise is a supplier-research resource I own. A directory entry is a candidate for investigation, not approval of a vendor or insurance product.
The business foundation checklist covers wider administration. Business registration, local work rules, taxation and personal insurance each need appropriate separate review. My business resources do not determine your insurance eligibility.
Frequently asked questions
Is one policy best for everyone visiting Bali? No. Residence, itinerary, activities and care needs determine the comparison. Obtain current applicable documents rather than selecting solely from a brand ranking.
Does a scooter rental establish insurance coverage? No. Review licensing, vehicle class, safety requirements and any required add-on. The rental transaction does not approve an insurance claim.
Does travel medical cover every canceled booking? No blanket conclusion follows from the product category. Cancellation, interruption and delay benefits have separate covered reasons and terms.
Should Essential and Complete be compared by price alone? Their stated purposes and billing units differ. Establish the coverage need and eligibility before comparing the total premium for matching dates.
Did this guide test claims or buy these policies? No. This is documentary research and a proposed selection process. Complete applicable contracts and individual eligibility need further verification.
Related guides
- SafetyWing for Bali: provider-specific questions
- SafetyWing Essential versus Complete
- SafetyWing coverage exclusions
- SafetyWing alternatives
- Remote business tools
Trevor Fenner is the founder of Ecommerce Paradise. His main projects are Ecommerce Paradise, Supplier Paradise, and Review Paradise, which is currently in development. TrevorFenner.com publishes research-based reviews and practical guides to online business tools and remote-work services, with clear affiliate disclosures.